Insurance Supplements: Key Takeaways
|

An insurance supplement is a formal, itemized request submitted to your insurance carrier for additional funds after the original claim estimate has already been approved. It covers legitimate costs — like hidden roof deck damage, code-required upgrades, or underpriced labor — that the adjuster’s first estimate didn’t include. If you’re staring at an insurance check that seems too low to cover the roof, siding, or window work your home actually needs, a supplement is very likely the reason, and the solution.
This guide explains exactly what an insurance supplement is, why it happens, how the process works, and what to expect when American Custom Contractors (ACC) handles one on your behalf.
What Is an Insurance Supplement, Exactly?
In plain terms, an insurance supplement is a revised estimate. After your insurance company’s adjuster inspects storm or wind damage and issues an initial scope of work and payout, the contractor doing the repair compares that scope against what the job actually requires. If there’s a gap — missing materials, missing labor, missing code items — the contractor documents it with photos, measurements, and line-item pricing, then submits that documentation to the carrier as a supplement request.
Supplements aren’t a negotiating tactic or a way to pad a bill. They’re a standard, carrier-recognized part of the property claims process, built into how insurance companies price and pay for roofing, siding, and window replacement, repair, and restoration work.
Why Do Initial Insurance Estimates Fall Short?
Adjusters typically write an initial estimate quickly, often after a brief roof or exterior inspection, and sometimes using aerial imagery or standardized software rather than a full tear-off inspection. That process is efficient, but it can’t always catch everything a code-compliant repair actually requires. Common gaps include:
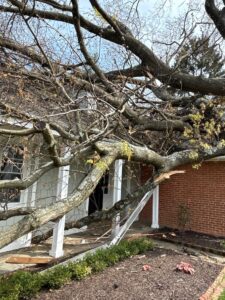
- Hidden damage: Rotted decking, damaged flashing, or saturated insulation that’s only visible once old roofing or siding is removed.
- Code upgrades: Local building codes may require items like ice-and-water shield, updated ventilation, or drip edge that weren’t in the original scope.
- Additional layers: Multiple layers of old shingles that add labor and disposal costs beyond what was estimated.
- Outdated pricing: Material and labor costs that have changed since the estimating software’s price list was last updated.
- Measurement differences: Roof or wall measurements that don’t match the actual dimensions of your home.
How the Insurance Supplement Process Works
- Initial inspection: Your insurance adjuster inspects the damage and issues a claim estimate and scope of work.
- Contractor review: Once work begins (or sometimes before), your contractor compares the adjuster’s scope against the real, on-site scope of work.
- Documentation: Any gaps are documented with photos, measurements, and itemized costs.
- Submission: The contractor submits the supplement request directly to the insurance carrier, along with supporting evidence.
- Carrier review: The insurance company reviews the request and approves, adjusts, or occasionally requests more information.
- Updated payout: Once approved, the carrier issues an updated payment reflecting the additional, necessary work.
Supplements can be submitted before work starts, during the project once hidden damage is exposed, or after completion if an oversight is discovered. Submitting earlier generally means a faster, smoother approval, which is why ACC reviews the adjuster’s scope closely before work begins whenever possible.
Who Files the Supplement — You or the Contractor?
Your contractor files it, not you. Filing a supplement means preparing a detailed, itemized estimate (often in the same Xactimate-based format insurance carriers use) with supporting photos and documentation, then communicating directly with the adjuster or carrier until it’s resolved. This is contractor-side work. As the homeowner, your role is simply to review and sign off on any changes to the agreed scope of work, and to ask your contractor questions any time something isn’t clear.
Is an Insurance Supplement the Same Thing as Overbilling?
No, and it’s worth addressing this directly. Some homeowners worry a contractor lowballs the original conversation just to tack on charges later. In a properly run supplement, that’s not what’s happening. A legitimate supplement is tied to specific, documented, necessary work — not an estimate written to be revised upward later. It also comes with real administrative cost to the contractor: preparing documentation, communicating with the carrier, and waiting on approval takes time and staff resources most contractors would rather not spend if the work weren’t genuinely needed.
That said, transparency is what separates a fair supplement from a bad one. You have the right to see exactly what’s being requested, why, and with what supporting documentation, before it’s submitted.
What This Looks Like When You Work With ACC
American Custom Contractors has served Maryland homeowners since 1972 and holds an Owens Corning Platinum Preferred Contractor designation. When we identify a gap between an adjuster’s estimate and the actual condition of your roof, siding, or windows, here’s what we commit to:
- We show you the photos and measurements behind any supplement before it’s submitted to your carrier.
- We explain, in plain language, exactly which items are being added and why they’re required — whether that’s a building code requirement or storm damage that wasn’t visible during the initial inspection.
- We communicate directly with your adjuster so you’re not stuck relaying messages back and forth.
- We never submit a supplement for work that isn’t documented and necessary.
If you’ve received an insurance estimate for roof, siding, or window damage and aren’t sure whether it covers everything your home needs, we’re happy to walk through it with you with a free estimate – no obligation, and no pressure to move forward.